In today’s financial panorama, understanding the nuances of bad credit personal loans is essential for individuals navigating life’s challenges. This case research presents the journey of Sarah, a 32-12 months-old advertising and marketing skilled, who found herself in a precarious financial state of affairs and sought a personal loan regardless of her poor credit score. By means of her experience, we’ll examine the advantages, disadvantages, and the broader implications of bad credit personal loans.
Background
Sarah had all the time been diligent about her funds until a collection of unlucky occasions derailed her stability. She misplaced her job in an unexpected firm downsizing, which led to a number of months of missed payments on her credit score playing cards and car loan. By the point she discovered a brand new job, her credit rating had suffered considerably, dropping to 580. With mounting debts and no financial savings, Sarah started to explore her choices for financial relief.
The need for a Personal Loan
Sarah’s immediate concern was to repay her bank card debt to avoid escalating interest charges, and she also needed funds to cowl her essentials whereas she settled into her new job. She shortly learned that her poor credit score would make securing a conventional loan tough; most lenders required a minimum credit score of 640. Confronted with restricted choices, she began to research bad credit personal loans.
Researching Loan Choices
Sarah found various lenders specializing in bad credit loans, together with on-line platforms. Many claim to supply loans to individuals with credit scores as low as 500. At first glance, the promise seemed appealing—but as she dug deeper, Sarah found the pitfalls associated with these loans. Many lenders charged exorbitant interest rates that might attain 30% or extra, significantly rising the full quantity she must repay.
Choosing a Lender
After cautious consideration, Sarah settled on a lender with slightly lower rates and a transparent price structure. She appreciated their willingness to supply instructional assets about managing funds put up-loan. Her loan approval course of was swift, and within days, she was introduced with the phrases of her loan: a $5,000 personal loan at an curiosity price of 24%. Whereas not very best, Sarah was in desperate need of funds and felt cornered by her circumstances.
Taking the Loan and Repayment Challenges
Initially, the loan supplied Sarah with the much-needed relief. She paid off her credit card debts promptly and managed to maintain her bills in check. Nonetheless, the excessive-interest charge of her new loan soon proved burdensome. Monthly payments consumed a considerable portion of her revenue, leaving her with little leftover for day-to-day expenses. This predicament pressured her to contemplate extra financial methods, akin to making a strict price range and taking on freelance work after hours to complement her income.
Sarah’s expertise highlights a standard concern confronted by these with bad credit: the battle between speedy monetary relief and long-term sustainability. The scenario was compounded when an unexpected medical bill hit, forcing her to rethink her monetary strategy.
Seeking Alternatives
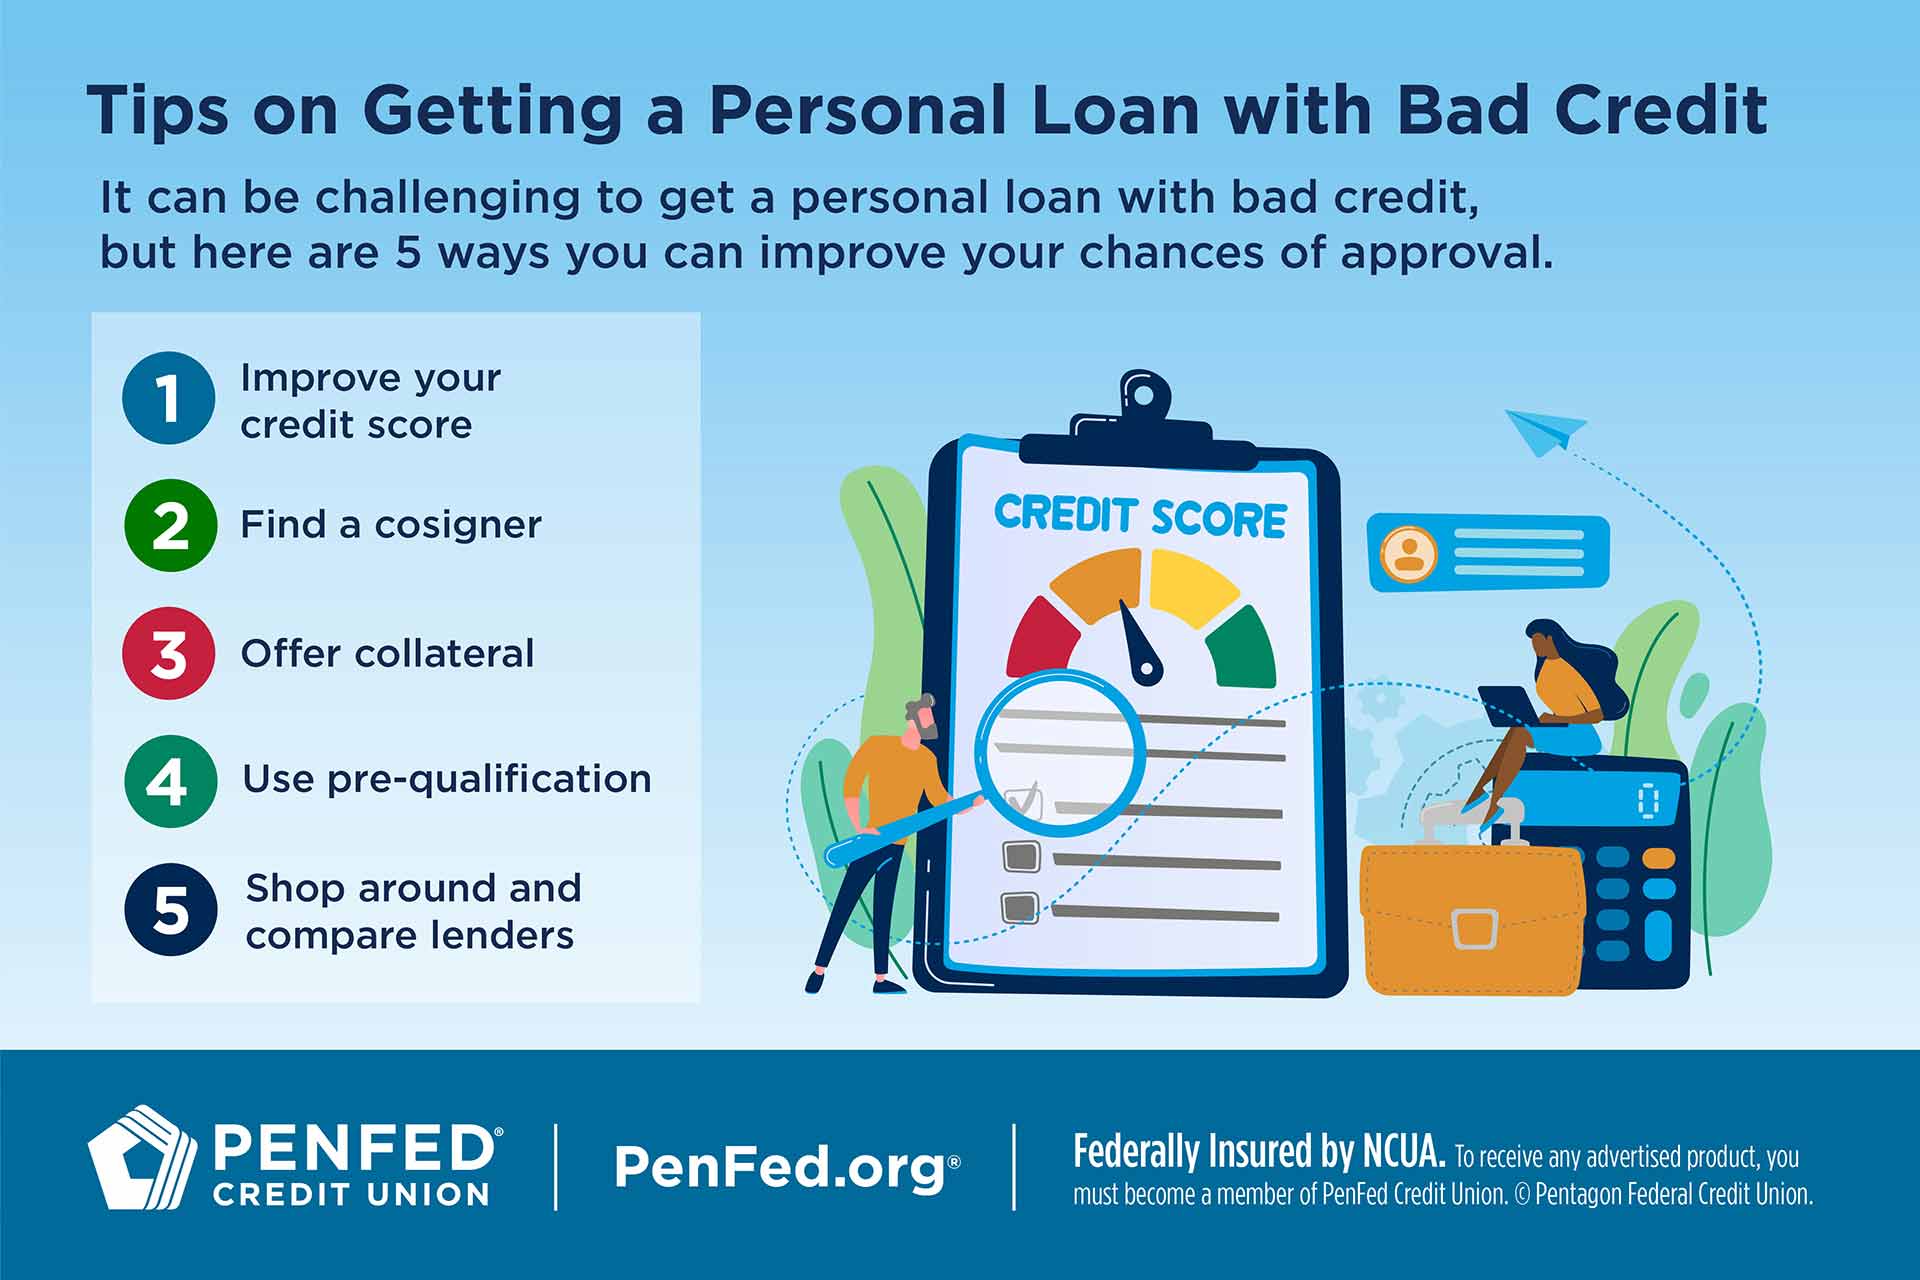
Realizing the burden of her present loan and the accumulating interest, Sarah began exploring options to manage her loan more effectively. She reached out to credit score counselors and started to consider debt consolidation choices. Additionally, she identified neighborhood sources, which provided entry to financial literacy workshops and loan repayment assistance applications. These avenues not only helped her in managing her present debt but in addition educated her on methods to improve her credit score rating over time.
Impact on Credit score Rating
Over the following few months, as Sarah diligently made her loan funds, she also worked on bettering her financial behavior. She decreased her credit card usage, started a savings plan, and ensured she paid all her bills on time. By the end of a year, Sarah’s credit rating recovered to 620, making her eligible for better loan choices in the future. This experience underscored an essential lesson: whereas bad credit personal loans can serve as a lifeline, they are not a everlasting answer.
Conclusion: Learning from Expertise
Sarah’s case exemplifies the challenges and potentialities inherent in bad credit personal loans. On one hand, these loans provided necessary funds during a important interval. Then again, the burden of high-curiosity charges can exacerbate monetary challenges and hinder general progress in the direction of monetary stability. The scenario emphasizes the significance of researching choices totally and understanding the terms and consequences associated with personal loans.
Moreover, Sarah’s journey highlights the necessity of bettering financial literacy among customers. Bad credit loans should not be a first resort but moderately a cease-hole resolution when no other choices can be found. By her struggles and eventual successes, Sarah realized to prioritize her monetary well being, establishing a foundation to build upon as she strikes forward.
In summary, bad credit personal loans can offer essential relief for those in monetary distress but come with significant risks. The trail to restoration entails extra than just securing a loan; it requires a commitment to sound monetary practices, ongoing schooling, and a proactive method to rebuilding creditworthiness. Sarah’s expertise serves as a testament to resilience and the opportunity of reclaiming control over one’s financial future.