Abstract
Emergencies can strike unexpectedly, usually leaving individuals and households in precarious monetary conditions. The rise of emergency loans as a potential resolution to fast financial distress has garnered attention in recent years. When you loved this informative article and also you desire to obtain details about Allbio kindly check out our page. This article explores the nature of emergency loans, their mechanics, advantages, challenges, and their total affect on financial resilience.
Introduction
The unpredictability of life events—such as medical emergencies, job loss, automobile repairs, and unexpected bills—can create significant stress and monetary turmoil. In such circumstances, people and families typically flip to emergency loans to bridge the financial gap. These loans are typically characterized by swift approval processes and speedy availability of funds, however their implications lengthen beyond mere financial relief. Understanding emergency loans is essential for grasping their function in promoting monetary resilience within the face of unforeseen difficulties.
The nature of Emergency Loans
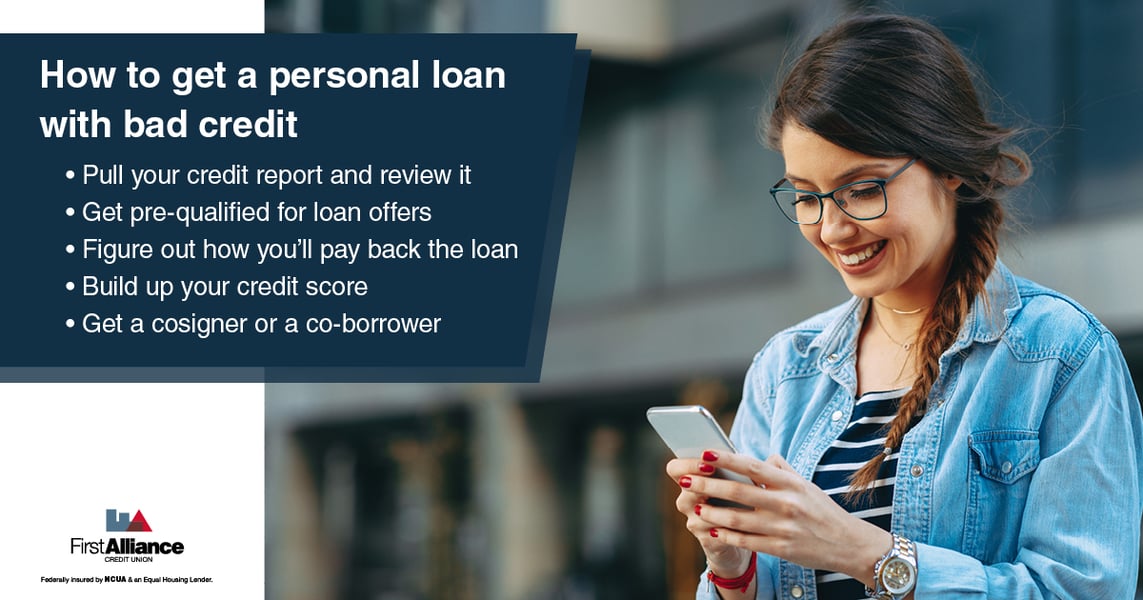
Emergency loans are a category of monetary products designed to supply quick entry to cash during urgent conditions. Not like conventional loans which may require extensive applications and lengthy approval instances, emergency loans are supposed for expedited access to funds. They'll take various forms, together with personal loans, payday loans, and credit traces, each with its unique features and repayment phrases.
- Personal Loans: Usually unsecured, personal loans can offer larger sums with relatively lower interest charges, offered the borrower's creditworthiness is passable.
- Payday Loans: Usually excessive-curiosity quick-time period loans, payday loans are often taken against the borrower's subsequent paycheck. These loans include important risks due to their excessive interest rates and potential for exacerbating monetary troubles.
- Credit Traces: These present borrowers with access to funds up to a sure limit, permitting flexibility in withdrawal and repayment. Credit score traces may be secured (backed by collateral) or unsecured.
Mechanics of Emergency Loans
The obtaining process for emergency loans typically involves a few vital steps. Initially, borrowers must consider their monetary scenario and decide the amount of money wanted. Upon choosing a lender—often online platforms or local financial institutions—borrowers fill out an application, which can require private identification, income verification, and employment details.
Upon submission, lenders can deliver approvals quickly, sometimes inside a couple of hours. Fund distribution can occur instantly or inside the following business day, relying on the loan agreement. However, the convenience of fast loans is accompanied by variable interest charges, repayment phrases, and potential fees—all components warranting cautious consideration on the borrower’s part.
Advantages of Emergency Loans
Emergency loans can serve as a lifeline for people facing unexpected expenses. The key benefits embrace:
- Fast Access to Money: The foremost benefit of emergency loans is the pace at which funds could be acquired. In a disaster, fast financial relief is crucial to mitigate quick worries.
- Flexibility: Many lenders provide completely different amounts, enabling borrowers to decide on a loan that aligns with their needs.
- Credit score Constructing Opportunities: For some borrowers, accountable management of emergency loans can enhance credit scores over time. Establishing a optimistic repayment history can benefit future borrowing.
- Help During Monetary Hardships: Emergency loans can provide a buffer against unexpected bills, reducing the chance of falling into severe monetary distress.
Challenges and Dangers
Regardless of their apparent advantages, emergency loans aren't with out drawbacks. Understanding these dangers is vital for potential borrowers:
- Excessive-Interest Charges: Many emergency loans, notably payday loans, come with exorbitant curiosity rates that can result in an unsustainable debt cycle.
- Brief Repayment Terms: Emergency loan repayment intervals are often temporary, forcing borrowers to settle debts rapidly or face increasing costs.
- Potential for Debt Trap: Borrowers who depend on emergency loans repeatedly might discover themselves in a vicious cycle of debt, where new loans have to be taken to pay off previous ones.
- Impression on Credit: Failure to repay loans on time can lead to a unfavourable impact on borrowers’ credit score scores, making future borrowing more difficult and dear.
Impact on Financial Resilience
Financial resilience refers to the ability to withstand and recuperate from financial shocks. Emergency loans can play a dual function in this process—they can both assist in quick restoration from financial distress and doubtlessly hinder long-term monetary health if not managed responsibly.
Emergencies can catalyze a re-analysis of financial health and habits. The availability of emergency loans can provide individuals the immediate relief they require, but reliance on these loans might deter them from growing sustainable monetary habits, similar to creating an emergency fund or pursuing monetary literacy.
To reinforce financial resilience effectively, it is essential for people to view emergency loans not as an extended-term answer however as a brief bridge in occasions of disaster. Consistent monetary training and higher access to alternative funding sources can empower people to build a more secure financial future.
Options to Emergency Loans
In search of options to emergency loans can typically provide more sustainable solutions. Some choices embody:
- Emergency Savings Funds: Building and sustaining an emergency fund that covers three to six months' worth of bills can serve as a buffer against unexpected monetary challenges.
- Credit Unions: Many credit unions provide low-interest personal loans with favorable terms for members, reducing the burden of excessive-curiosity charges that accompany payday loans.
- Assistance Programs: Community organizations and authorities packages might present financial help for specific emergencies, resembling medical expenses or housing assist.
- Negotiating with Creditors: Overtly speaking with creditors about monetary struggles can typically lead to versatile fee preparations or short-term relief.
Conclusion
Emergency loans may be an important tool in navigating the speedy aftermath of financial shocks. Whereas they provide swift access to funds, it is important for borrowers to be aware of the accompanying dangers and to approach them with warning. To foster financial resilience, people are encouraged to think about training, sustainable financial practices, and different sources alongside emergency loans. By doing so, they can higher prepare for the uncertainties of life whereas guaranteeing long-time period monetary wellbeing.
References
(References would usually be included right here in a scientific article however are omitted for brevity.)